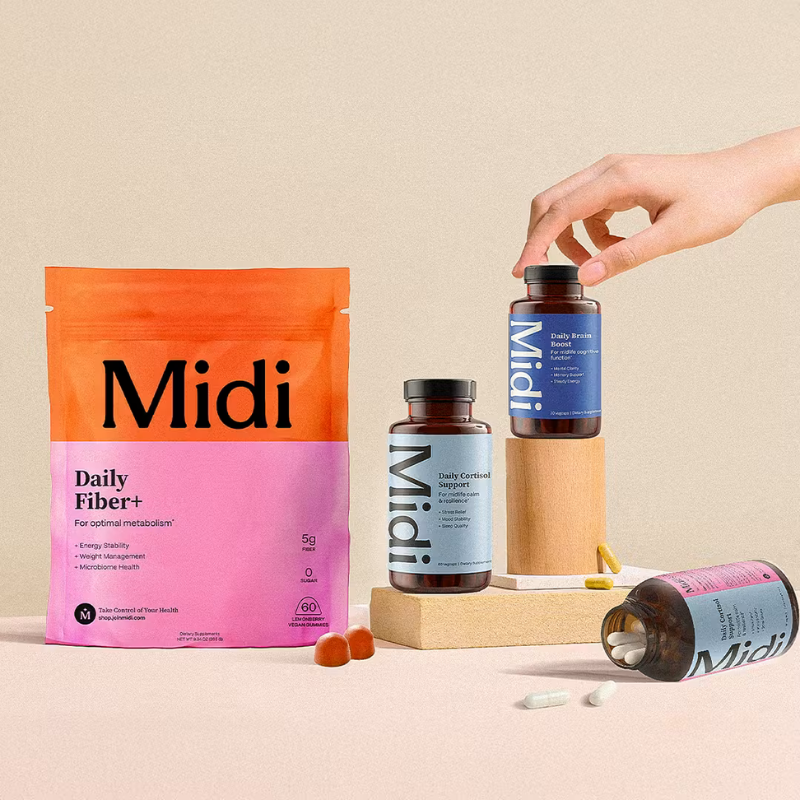
Experience expert, personalized menopause care tailored to your unique journey with Midi Health. As a virtual clinic built by clinicians for women, we provide science-backed, insurance-covered medical support to help you manage symptoms and navigate midlife health transitions with confidence. From hormonal therapy to integrative wellness plans, our dedicated providers work directly with you to create a customized path toward relief and long-term vitality. Stop navigating hormonal changes alone – choose Midi Health for accessible, compassionate care that puts your needs first. Empower yourself with the medical expertise, clear guidance, and support required to thrive through every stage of your life.
Description
Advertorial / Sponsored Content. This article contains an affiliate relationship. Midi Health provides access to licensed clinicians through independent, affiliated medical groups; the exact billing entity and provider affiliation may vary by state. This article is for informational purposes only and does not constitute medical advice, diagnosis, or treatment. Always consult a qualified healthcare provider for medical questions or concerns, and verify current insurance coverage, pricing, and provider credentials directly with Midi Health before booking.
Menopause and perimenopause care has historically been an underserved corner of women’s health, with many patients reporting that their symptoms were dismissed or under-treated by general practitioners who didn’t specialize in this area. Midi Health has built its business specifically around that gap, offering virtual visits with clinicians who focus on perimenopause, menopause, and related midlife health concerns, with a structure built to work with health insurance rather than functioning purely as a cash-pay subscription service. That insurance-integrated model is actually one of the more distinctive things about Midi Health compared to many other women’s telehealth platforms, which tend to operate on a flat monthly cash-pay basis. In this article, we’ll walk through how Midi Health’s insurance billing actually works, what real out-of-pocket costs tend to look like, what credentials and accreditations back the platform, and where its optional GLP-1 weight management add-on fits into the picture, including the same compounded-versus-FDA-approved distinction that applies to any GLP-1 telehealth service. As with any healthcare decision, the goal here is to give you a clear, accurate picture of how the platform actually works so you can have an informed conversation with your insurer and with a Midi clinician, rather than relying on marketing language alone.
Midi Health’s Structure: Platform, Affiliated Medical Groups, and Insurance Billing
Midi Health operates as a virtual care platform that connects patients with clinicians specializing in perimenopause, menopause, and related midlife health concerns, delivered through affiliated medical groups staffed by licensed providers, including physicians and nurse practitioners with menopause-specific training. Midi Health holds accreditation from the National Committee for Quality Assurance (NCQA), a nonprofit organization that evaluates health plans and care organizations against quality and process standards, and is verified by LegitScript, a third-party organization that reviews telehealth and online pharmacy platforms for legal and safety compliance. What sets Midi Health apart structurally from many telehealth platforms in the women’s health space is that it’s built to bill through health insurance rather than operating purely as a flat-fee, direct-pay service, a meaningfully different financial model that comes with its own complexity, discussed in detail below. As of recent updates to its billing process, Midi requires a card on file at registration, though patients are not charged at the time of booking; the actual visit fee is processed only after an appointment is completed, and billing for insured patients is then reconciled against whatever your specific plan covers.
How Insurance Billing Actually Works at Midi Health
Understanding Midi Health’s insurance model is probably the single most important thing to get right before booking, since actual out-of-pocket costs vary considerably based on your specific plan rather than following one flat, predictable price. According to Midi Health’s own guidance, if you use insurance for your visit, you will typically be billed later for any out-of-pocket costs not covered by your plan, meaning you generally won’t pay the full amount upfront at the time of your appointment. Midi states that most patients, on average, pay around $50 out-of-pocket per visit when using insurance, though a new patient visit may carry a deductible responsibility of up to $250, and a follow-up visit up to $150, on top of which standard copayments and coinsurance may also apply depending on your specific plan design. Because every insurance plan differs in deductible status, coinsurance percentage, and copay structure, Midi is explicit that it cannot predict your exact cost and recommends contacting your insurer directly to understand your specific plan’s out-of-pocket exposure before your visit. It’s also important to understand Midi’s coverage limitations clearly: Midi Health and its affiliated medical groups are not enrolled with, and do not participate in, state healthcare programs such as Medicaid or Medi-Cal, and cannot treat patients covered by those programs, even on a self-pay basis. Midi is also not covered by Medicare or Medicare-related plans, though Medicare beneficiaries can be seen as self-pay patients, with the understanding that no claims related to those visits, medications, or associated services can be submitted to Medicare. HSA and FSA funds can generally be used to cover copays and other Midi-related costs, which is worth knowing if you’re weighing how to budget for care.
What Does a Midi Health Visit Actually Cost?
Because Midi Health’s pricing depends so heavily on insurance status, it’s worth separating out what’s known for insured versus self-pay (cash-pay) patients. For patients using insurance, Midi’s own materials point to an average out-of-pocket cost of roughly $50 per visit, though your actual cost depends entirely on your plan’s specific deductible, copay, and coinsurance terms, and could reasonably be higher or lower than that average depending on where you stand relative to your deductible for the year. For patients without applicable insurance coverage or who choose to pay out of pocket, third-party reporting and patient-shared accounts have cited cash-pay initial consultation pricing in the range of roughly $200 to $250, though we were not able to independently confirm an exact, current self-pay rate directly from Midi’s own pricing page at the time of writing, and this figure should be confirmed directly on Midi’s official Pricing & Insurance page before booking, since pricing structures and rates are subject to change. It’s also worth noting that the visit fee itself is separate from the cost of any labs or prescription medications a clinician might order, which represent additional costs beyond the base consultation price, insured or not.
What Conditions and Services Does Midi Health Cover?
Midi Health’s core focus is perimenopause and menopause care, covering the wide range of symptoms associated with that life stage, including hot flashes, sleep disruption, mood changes, and other hormonal symptoms, with clinicians who can discuss and prescribe hormone replacement therapy (HRT) and non-hormonal alternatives where appropriate. Beyond core menopause care, Midi’s service lines reportedly extend into related areas, including general midlife wellness and longevity-focused care, sexual wellness, mood and cognitive concerns sometimes associated with hormonal changes, hair and skin concerns, sleep, and support for patients navigating menopause alongside a cancer history or survivorship care, an area where hormone-related treatment decisions can be especially complex and benefit from a specialist’s input. Midi has also added a GLP-1 weight management service line, discussed in more detail below, reflecting a broader trend of menopause-focused platforms expanding into weight management given the overlap between menopausal hormonal changes and metabolic health. It’s worth noting that some services, testosterone prescribing in particular, have been described inconsistently across different third-party sources, with at least one patient account suggesting Midi historically prescribed only FDA-approved medications and did not prescribe testosterone off-label for women, while Midi’s own more recent site materials reference testosterone therapy as an offered service; given this discrepancy, anyone specifically interested in testosterone therapy should confirm current availability directly with Midi before assuming it’s included in your specific care plan.
Midi Health’s GLP-1 Weight Management Option
Midi Health offers GLP-1 weight management as an additional service line, and it’s important to understand that this operates somewhat differently from Midi’s core, insurance-billed menopause care. GLP-1 medications for weight management specifically are generally not covered by most commercial insurance plans, which means this service line tends to function more like the cash-pay subscription model common across other GLP-1 telehealth platforms, separate from Midi’s insurance-integrated visit structure for menopause care. As with any GLP-1 telehealth service, the same fundamental distinction applies here: compounded semaglutide and compounded tirzepatide, prepared by licensed compounding pharmacies, are not FDA-approved medications, unlike brand-name products such as Wegovy or Zepbound, which have completed the FDA’s full drug approval process. Third-party reporting on Midi’s GLP-1 pricing structure has cited compounded medication costs in a range of roughly $150 to $350 per month depending on dose and pharmacy, separate from any platform or visit fee, though as with all pricing in this space, current, exact figures should be confirmed directly on Midi’s official website rather than relied upon from third-party estimates, since GLP-1 telehealth pricing across the industry has shown meaningful movement over time. If you’re specifically interested in Midi’s GLP-1 program, it’s worth asking directly whether a given prescription would be compounded or an FDA-approved brand product, since this affects both cost and the regulatory framework governing your specific medication.
Provider Credentials and the Value of Specialization
One of the more meaningful value propositions behind a platform like Midi Health is provider specialization: many patients report that their primary care physician or general gynecologist didn’t have deep, current expertise in menopause management specifically, a gap that’s been documented more broadly in general medical training, where menopause-specific education has historically been limited in many residency programs. A platform built specifically around clinicians with concentrated menopause and midlife hormone expertise can offer a different depth of care than a generalist visit, particularly for patients with complicated presentations, such as a personal or family cancer history that complicates hormone therapy decisions, or symptoms that were previously dismissed or inadequately addressed elsewhere. That said, specialization in a telehealth format doesn’t eliminate the general limitations of remote care: a virtual visit, however well-informed the clinician, doesn’t replace an in-person physical exam or ongoing relationship with a local primary care provider, and complex cases may still benefit from in-person specialist referral where a Midi clinician determines that’s appropriate.
Employer Benefits and Broader Access
Midi Health has reportedly established partnerships with large employers to offer its services as an employee health benefit, which is a distribution model distinct from most direct-to-consumer telehealth platforms and may reflect a level of institutional vetting beyond what a typical cash-pay startup receives, since large employers generally conduct their own due diligence before adding a vendor to their benefits package. If your employer offers Midi Health as a benefit, it’s worth checking your specific plan documents, since employer-sponsored access may come with different, and potentially more favorable, cost-sharing terms than what’s available to the general public purchasing insurance-billed or cash-pay visits independently.
Is Midi Health Legitimate?
Midi Health’s NCQA accreditation and LegitScript verification are genuine, independently awarded credentials that go beyond simple self-attestation, and its insurance-billing model, while more operationally complex than a flat-fee subscription, reflects real integration with the traditional healthcare payment system rather than existing purely outside of it. Employer benefit partnerships add another layer of third-party vetting. That said, the complexity of insurance billing means “legitimate” doesn’t translate to “predictable cost,” and patients should go in expecting to do some homework, contacting their insurer to understand plan-specific costs, and confirming current cash-pay rates directly with Midi, rather than assuming a single, simple price applies to everyone. As with any telehealth platform, verifying your specific coverage, current pricing, and the specific credentials of the clinician you’d be working with are reasonable, worthwhile steps before booking.
Questions Worth Asking Before You Book
Before scheduling a Midi Health visit, it’s worth calling your insurance company directly and asking specifically whether Midi Health’s affiliated providers are in-network for your plan, since in-network status significantly affects your out-of-pocket cost. Ask about your current deductible status for the year, since a new patient visit deductible of up to $250 is a meaningfully different financial commitment depending on whether you’ve already met your deductible elsewhere. If you’re interested in the GLP-1 program specifically, ask directly whether Midi would prescribe a compounded or FDA-approved medication for your situation, and get a clear, current price for both the visit and the medication before committing. If you have a complex medical history, including a personal or family cancer history relevant to hormone therapy decisions, come prepared with your relevant records and be direct with your clinician about wanting a thorough discussion of the risks and benefits specific to your situation, rather than a generic treatment recommendation.
Conclusion
Midi Health occupies a distinctive position in the women’s telehealth space by building its core menopause and perimenopause care around insurance billing rather than a flat cash-pay subscription, backed by NCQA accreditation, LegitScript verification, and reported employer benefit partnerships. For patients with insurance coverage that includes Midi’s affiliated providers in-network, this structure can meaningfully reduce out-of-pocket costs compared to a pure cash-pay model, though it also introduces the general unpredictability that comes with any insurance-billed healthcare service. Its optional GLP-1 weight management add-on functions more like a typical cash-pay telehealth offering, and carries the same compounded-versus-FDA-approved distinction that applies across this medication category generally. For someone looking for specialized menopause care and who has confirmed their insurance coverage and out-of-pocket exposure ahead of time, Midi Health may offer meaningful value; for anyone considering the platform, calling your insurer and reviewing current pricing directly on Midi’s website before booking are the two most useful steps you can take.
Midi Health FAQs
Does Midi Health take my insurance?
Coverage depends on your specific plan and Midi’s provider network in your state. Contact your insurer directly to confirm whether Midi’s affiliated providers are in-network for you.
How much does a Midi Health visit cost?
With insurance, patients pay an average of around $50 out-of-pocket per visit, though a new patient deductible of up to $250 may apply. Self-pay rates have been reported around $200–$250 by third parties; confirm current pricing directly with Midi.
Does Midi Health accept Medicare or Medicaid?
No. Midi does not participate in Medicaid/Medi-Cal and cannot treat those patients even as self-pay. Midi is not covered by Medicare, though Medicare beneficiaries can be seen as self-pay patients without submitting claims.
Can I use my HSA or FSA?
Yes, generally for copays and other Midi-related service costs.
What conditions does Midi Health treat?
Primarily perimenopause and menopause symptoms, with additional service lines including weight management, sexual wellness, mood and cognitive concerns, sleep, and cancer/survivorship-related hormone care.
Is Midi Health’s GLP-1 program covered by insurance?
Generally no. GLP-1 medications for weight management are typically not covered by commercial insurance and function more like a cash-pay service.
Is compounded semaglutide through Midi the same as Wegovy?
No. Compounded semaglutide is prepared by a licensed compounding pharmacy and is not FDA-approved, unlike brand-name Wegovy or Zepbound.
Does Midi Health prescribe testosterone for women?
Reports vary by source and may reflect changes over time; confirm current availability directly with Midi if this is important to your care plan.
Is Midi Health accredited?
Yes, Midi Health holds NCQA accreditation and is LegitScript verified.
Is Midi Health available through my employer?
Possibly. Midi has reportedly partnered with large employers to offer its services as a benefit; check your specific benefits documentation.